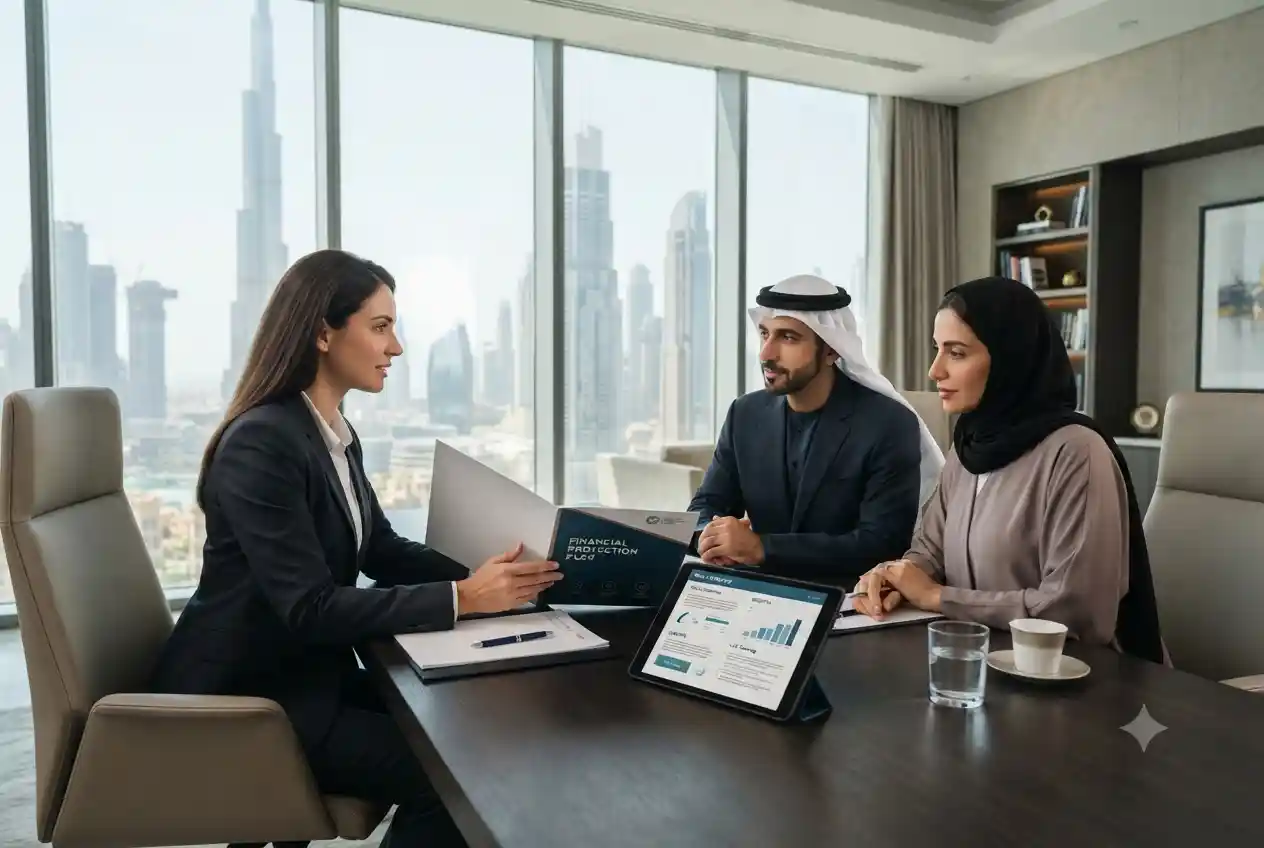
Home insurance Dubai is an important consideration for homeowners, tenants and landlords who want financial protection against unexpected damage or loss affecting a property and its contents. A suitable policy can protect more than the physical building. Depending on the coverage selected, it may also protect furniture, electronics, personal belongings and certain liabilities connected with the home.
Home insurance is not a one-size-fits-all product. A villa owner may have different insurance needs from someone renting an apartment, while a landlord may require cover designed around a rented property rather than personal possessions. Understanding these differences can help Dubai residents choose protection that matches their circumstances.
When comparing home insurance, price is only one factor. Policy limits, exclusions, deductibles, accidental damage, alternative accommodation, contents protection and liability benefits can all affect the practical value of a policy. The cheapest quotation may not provide sufficient protection when a major loss occurs.
What Is Home Insurance in Dubai?
Home insurance is designed to protect a residential property and/or its contents against specified insured risks. The exact coverage depends on the policy and whether the customer selects buildings insurance, contents insurance or a combined package.
Buildings cover generally relates to the physical structure of a property. Depending on the policy, this can include elements such as walls, floors, ceilings, permanent fixtures and other parts of the building that are specifically defined in the policy.
Contents insurance focuses on belongings inside the home. This can include furniture, appliances, electronics, clothing and other personal possessions, subject to the policy’s definitions, limits and exclusions.
Some Dubai home insurance products combine both forms of protection, while others allow customers to choose the sections that are relevant to them.
Is Home Insurance Mandatory in Dubai?
Home insurance should not be confused with mandatory insurance requirements that apply to other types of risk, such as motor insurance. For many homeowners and tenants, residential property insurance is purchased primarily as financial protection rather than because every residential property must carry a standard home insurance policy.
However, specific contractual requirements can apply. A mortgage provider, landlord, property management company or tenancy arrangement may require certain insurance protection. The exact requirement depends on the relevant agreement and circumstances.
Homeowners and tenants should therefore check their mortgage, lease and property documents to determine whether a particular type of insurance is required.
What Does Home Insurance Dubai Usually Cover?
The scope of cover varies between insurers, but home insurance can protect against several common risks when they are included in the policy.
- Fire and smoke damage.
- Water damage from specified insured events.
- Storm or weather-related damage where covered.
- Burglary or theft of insured contents.
- Accidental damage where the selected policy includes it.
- Damage to specified building components.
- Loss or damage to personal belongings.
- Alternative accommodation following an insured event, where included.
- Personal or property liability under applicable policy terms.
Not every policy includes all of these protections automatically. The policy schedule and wording should be checked carefully, particularly for high-value possessions and accidental damage.
Buildings Insurance vs Contents Insurance
Buildings Insurance
Buildings insurance is intended to cover the physical property and permanent structures or fixtures identified by the policy. For a villa owner, this may include the main structure and certain permanently installed elements.
For an apartment owner, the distinction can be more complicated because some structural components may fall under the building owner’s or owners’ association’s arrangements. Before buying separate buildings cover, apartment owners should understand what is already insured by the building management or relevant property structure.
Contents Insurance
Contents insurance protects personal possessions inside the home. This can be particularly valuable for tenants because they may not need to insure the building itself but can still have substantial financial exposure if furniture, electronics, clothing or other belongings are stolen or damaged.
Tenants should therefore not assume that the landlord’s building insurance protects their personal possessions. The landlord’s policy and the tenant’s contents are separate risks.
Combined Home Insurance
A combined policy can provide buildings and contents protection under one insurance arrangement. This can be convenient for homeowners who want protection for both the property and belongings.
However, convenience should not replace careful comparison. Check the separate limits, deductibles, exclusions and valuation basis for both buildings and contents.
Home Contents Insurance Dubai
Home contents insurance Dubai is particularly relevant for tenants and homeowners who want to protect belongings kept inside their property. Contents can represent a substantial financial investment even when the building itself is insured separately.
Common household contents can include:
- Furniture and furnishings.
- Televisions and entertainment equipment.
- Computers and other electronics.
- Kitchen appliances.
- Clothing and personal belongings.
- Sports equipment.
- Selected jewellery and valuables, subject to policy limits.
High-value items may require separate declaration or may be subject to specific sub-limits. A standard contents policy should therefore not be assumed to provide unlimited protection for jewellery, watches, artwork, electronics or other expensive possessions.
Home Insurance for Tenants in Dubai
Renters have a different insurance profile from homeowners. A tenant generally does not own the building, but they may have significant personal possessions that would be expensive to replace after theft, fire, water damage or another insured event.
Contents insurance can therefore be useful for renters. Depending on the policy, tenants may also receive personal liability protection that can help with certain claims involving third-party injury or property damage.
For example, accidental damage originating from a rented apartment can potentially create financial exposure. Whether an insurance policy responds depends on the exact circumstances and policy wording, so renters should review the liability section carefully.
Home Insurance for Landlords in Dubai
Landlords have different priorities because they own the property but may not occupy it. Their insurance needs can include protection for the building, fixtures and other property-related risks.
A landlord may also need to consider loss of rental income following certain insured events. Some policies can provide this type of benefit when specified conditions are met, but it should never be assumed to be included automatically.
Landlords should also consider how tenant-related risks are addressed and whether any policy conditions apply when the property is rented to another person.
Home Insurance Abu Dhabi and Other UAE Emirates
Although this article focuses on home insurance Dubai, similar insurance principles apply across the UAE. Residents researching home insurance Abu Dhabi, Sharjah, Ajman or other emirates should still compare the specific policy terms and insurer requirements applicable to their property.
The location of the property can influence factors such as risk assessment, property characteristics, building type and available insurance products. Customers should therefore provide accurate information about the property when requesting a quotation.
Rather than assuming that a policy marketed for Dubai will automatically have identical terms elsewhere, check the geographic scope and applicable conditions before purchasing.
How Much Does Home Insurance Dubai Cost?
The cost of home insurance depends on the level of protection and the risk characteristics of the property and its contents. There is no universal premium that applies to every home.
Factors that can influence pricing include:
- Property type and location.
- Estimated rebuilding or replacement value.
- Value of household contents.
- Selected coverage limits.
- Claims history.
- Security features.
- Deductible or excess.
- Optional benefits.
- Whether buildings, contents or both are insured.
A villa with high-value contents will generally present a different insurance requirement from a small rented apartment with modest belongings. The appropriate coverage limit should reflect the actual financial exposure rather than an arbitrary number chosen simply to reduce the premium.
How to Calculate Your Home Contents Value
One of the most common mistakes when buying contents insurance is underestimating the total replacement value of belongings. Owners and tenants may remember expensive electronics and furniture but overlook clothing, kitchen equipment, appliances and smaller items that collectively represent significant value.
A practical approach is to create an inventory of the major possessions in each room. Record approximate replacement values and retain receipts, photographs or other evidence for expensive items where available.
For high-value possessions, ask the insurer whether individual declaration is required. Some policies impose specific limits on categories such as jewellery, watches, cash, artwork and portable electronics.
What Does Home Insurance Usually Exclude?
Home insurance does not cover every possible form of damage. Exclusions are an essential part of the policy and can determine whether a claim is accepted.
Depending on the policy, exclusions can include:
- Normal wear and tear.
- Gradual deterioration.
- Damage resulting from inadequate maintenance.
- Uninsured causes or events outside the policy definition.
- Certain high-value possessions that were not declared.
- Losses exceeding policy limits.
- Specific types of water damage or leakage depending on the wording.
- Intentional damage.
Customers should pay particular attention to the difference between sudden accidental damage and gradual deterioration. Insurance is generally designed around insured events rather than the ordinary maintenance of a property.
Does Home Insurance Cover Water Damage?
Water damage is a common concern for homeowners and tenants, but the source of the water and the circumstances of the incident can affect coverage.
A sudden insured escape of water may be treated differently from long-term seepage, poor maintenance or an unresolved plumbing problem. The policy wording determines whether the particular event is covered.
If a leak occurs, document the damage promptly, take photographs and contact the relevant building management or maintenance provider where appropriate. If you intend to make an insurance claim, follow the insurer’s notification procedure and preserve relevant evidence.
Does Home Insurance Cover Theft?
Contents policies can provide protection against theft when the theft falls within the insured circumstances and all applicable policy conditions are satisfied.
However, theft claims can involve requirements concerning forced entry, security measures, evidence of ownership and reporting to the authorities. Some categories of property can also have separate limits.
Keep receipts, photographs and other ownership records for valuable items. These documents can be useful when demonstrating the existence and value of insured possessions.
Does Home Insurance Cover Jewellery and Valuables?
Jewellery, watches, artwork and other valuables often require additional attention because policies may impose category-specific limits. A customer with expensive possessions should not assume that the standard contents limit provides sufficient protection.
Ask the insurer whether valuable items must be individually specified and whether professional valuation documents are required. Also check whether the policy provides protection inside and outside the home, because portable valuables can be treated differently from items permanently kept at the insured property.
What Is Personal Liability Cover?
Some home insurance policies include personal liability protection. This can provide financial protection against certain claims where the insured becomes legally liable for injury to another person or damage to third-party property, subject to the policy conditions.
Liability cover can be particularly relevant to homeowners and tenants because accidents involving visitors, neighbouring properties or other third parties can result in unexpected costs.
However, liability insurance is not unlimited. Check the applicable limit, exclusions and definition of covered liability before relying on it.
Should You Choose AXA Home Insurance Dubai?
AXA home insurance Dubai may appear in searches from residents comparing established insurance brands, but choosing a provider should involve more than brand recognition. Customers should compare the actual policy benefits, limits, exclusions, claims process, excess and service arrangements.
A recognizable insurer can offer a useful starting point for comparison, but the best policy is ultimately the one whose coverage matches the customer’s property and financial risks. Insurance products and branding can also change over time, so current product details should always be confirmed directly with the provider.
How to Choose the Right Home Insurance Dubai Policy
Start by identifying what you actually need to insure. A homeowner may need both building and contents protection, while a tenant may focus primarily on contents and personal liability.
Then estimate the replacement value of the property and belongings. Avoid deliberately underinsuring your home simply to reduce the premium, because insufficient limits can leave a substantial financial gap after a major loss.
When comparing policies, check:
- Buildings coverage limit.
- Contents coverage limit.
- Accidental damage protection.
- Theft and burglary coverage.
- Water damage coverage.
- Alternative accommodation benefits.
- Personal liability limit.
- Valuables and jewellery sub-limits.
- Deductible or excess.
- Claims reporting requirements.
- Policy exclusions.
How to Make a Home Insurance Claim
If an insured incident occurs, contact the insurer as soon as reasonably possible and follow the claims instructions provided in the policy.
Depending on the incident, useful evidence can include photographs of the damage, invoices, purchase receipts, police reports, repair estimates and correspondence with building management or contractors.
Do not dispose of damaged property before confirming whether the insurer needs to inspect it, unless immediate action is necessary for safety or to prevent further damage. Keep records of emergency repairs and notify the insurer according to the applicable procedure.
Why Comparing Home Insurance Matters
Home insurance policies can look similar at first glance while differing significantly in their limits and exclusions. One policy may offer a lower premium but provide less protection for accidental damage, valuables or alternative accommodation.
Comparing policies on an equivalent basis makes the process more meaningful. If one quotation includes contents coverage of a certain amount and another does not, the lower premium is not necessarily a better deal.
For Dubai residents, the objective should be to find an appropriate balance between premium, coverage and the amount of risk retained personally.
Closing Insight
Home insurance Dubai can provide valuable financial protection for homeowners, tenants and landlords facing unexpected property damage, theft, liability and other insured risks. The most suitable policy depends on who owns the property, who occupies it, what needs to be protected and how much financial risk the customer can reasonably retain.
Buildings insurance and contents insurance address different needs, while optional benefits such as accidental damage, alternative accommodation and liability protection can further change the value of a policy. High-value belongings may also require special attention or individual declaration.
Before purchasing house insurance, compare current quotations and read the policy wording carefully. Check coverage limits, exclusions, deductibles and claims requirements rather than choosing solely on price. A well-matched policy can provide greater confidence that your home and belongings have meaningful financial protection when an unexpected event occurs.