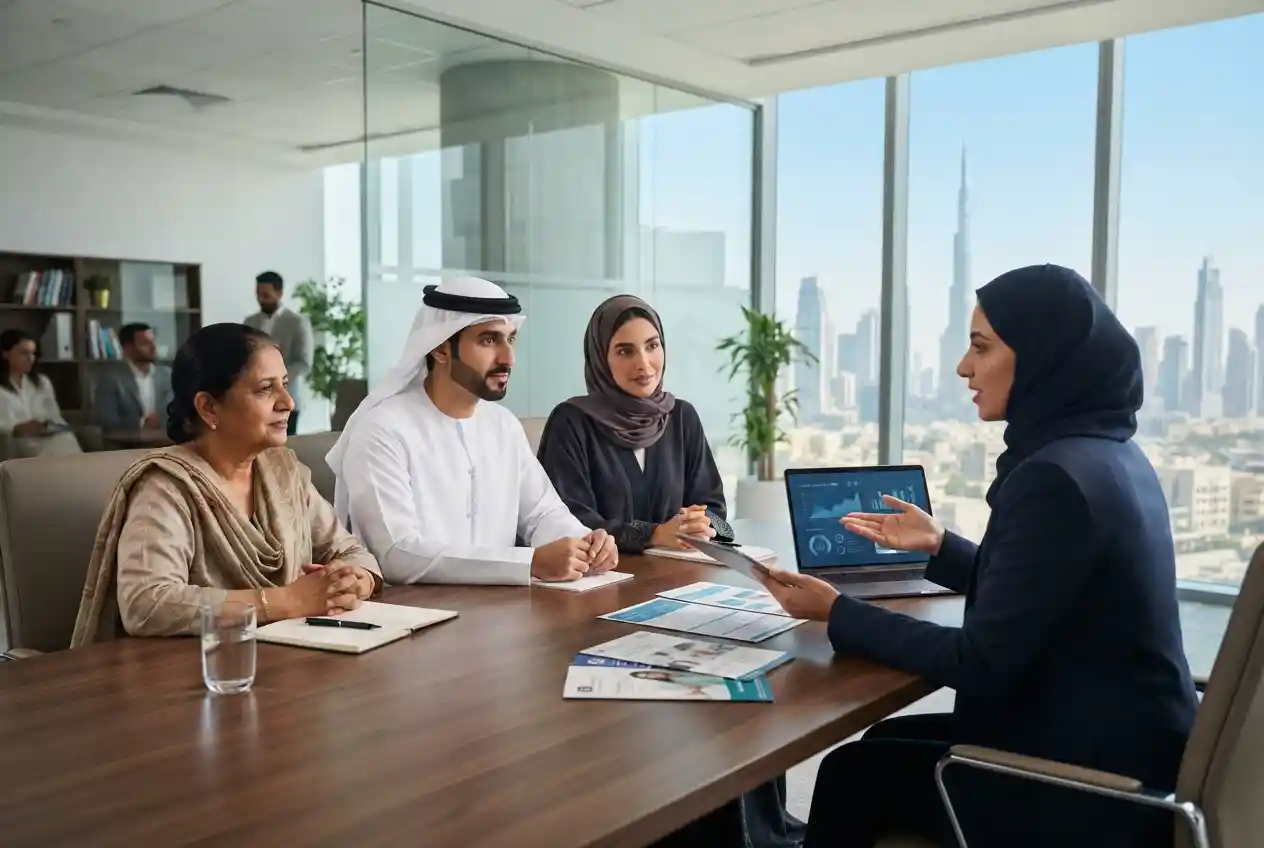
Finding the best healthcare insurance in the UAE is not simply a matter of choosing the cheapest policy. A suitable plan needs to match your healthcare needs, location, preferred hospitals and clinics, budget, family situation and level of coverage. A policy with a low premium may have a limited provider network or higher out-of-pocket costs, while a more comprehensive plan may provide broader access and additional benefits.
Health insurance is particularly important in the UAE because insurance requirements and healthcare regulations vary by emirate. The UAE Government states that health insurance is mandatory in Abu Dhabi and Dubai, while arrangements in other emirates can differ.
For residents, employees, families and employers, understanding how medical insurance works can make it easier to compare policies and avoid unexpected expenses. This guide explains the main types of cover, what to check before buying a plan and how to choose a policy that provides appropriate protection.
What Is Healthcare Insurance?
Healthcare insurance, commonly called health insurance or medical insurance, helps cover eligible healthcare expenses according to the terms and conditions of an insurance policy. Depending on the plan, covered services can include consultations, diagnostic tests, hospitalisation, emergency treatment, medicines and maternity care.
Insurance does not necessarily mean that every medical expense is paid in full. Policies can include deductibles, coinsurance, copayments, annual limits, exclusions and provider-network restrictions.
Understanding these details is essential when comparing health insurance plans because two policies with similar premiums can provide very different levels of protection.
Is Health Insurance Mandatory in the UAE?
Health insurance requirements depend on the emirate and the individual’s circumstances. The official UAE Government platform confirms that health insurance is mandatory in Abu Dhabi and Dubai.
Dubai has a mandatory health insurance framework, and the Dubai Health Insurance Corporation operates under the Dubai Health Authority to manage and supervise health insurance in the emirate.
Dubai’s framework includes a minimum level of coverage known as the Essential Benefits Plan. DHA information explains that Dubai’s mandatory system requires applicable employees and residents to have basic health insurance coverage, while sponsors have responsibilities concerning dependants and domestic workers.
Because regulations and policy requirements can change, residents should confirm current requirements with the relevant authority before purchasing or renewing a policy.
What Makes the Best Healthcare Insurance?
There is no single insurance policy that is best for every person. The right plan depends on your individual circumstances.
When comparing the best healthcare insurance options, consider the following factors:
- Annual premium
- Annual coverage limit
- Hospital and clinic network
- Outpatient coverage
- Inpatient coverage
- Emergency treatment
- Maternity benefits
- Prescription medicine coverage
- Diagnostic testing
- Copayments and deductibles
- Pre-existing condition rules
- Geographic coverage
- Waiting periods
- Exclusions
- Claims process and customer support
A good policy should provide a reasonable balance between cost and meaningful coverage rather than focusing on only one feature.
Health Insurance Plans in the UAE
Health insurance plans can vary from basic policies designed to meet minimum requirements to comprehensive plans offering wider provider networks and additional benefits.
Basic Health Insurance
Basic plans generally focus on essential healthcare services and may be suitable for individuals primarily concerned with meeting mandatory requirements and protecting themselves against common medical expenses.
In Dubai, the Essential Benefits Plan establishes a minimum level of coverage for eligible residents. DHA information describes benefits including inpatient and outpatient healthcare, maternity services, preventive services, vaccines and immunisations, subject to the applicable terms and conditions.
Comprehensive Health Insurance
Comprehensive plans can provide broader coverage than minimum mandatory packages. Depending on the insurer and policy, they may offer access to a larger network of hospitals and clinics, higher annual limits, broader geographical coverage and additional services.
These plans can be useful for families, frequent healthcare users and professionals who want greater flexibility when selecting providers.
Family Health Insurance
Families should compare policies based on the needs of every covered member. Children, older dependants and adults may have different healthcare requirements.
Parents should check paediatric coverage, emergency services, specialist consultations, medicines and hospital access. If maternity coverage is important, the policy’s maternity benefits and waiting periods should be reviewed before purchasing.
International Health Insurance
Some policies provide healthcare coverage outside the UAE or offer international treatment options. These plans can be relevant for people who travel frequently or want access to medical services in other countries.
However, international coverage can significantly affect the premium. Buyers should determine whether worldwide coverage is genuinely necessary before paying for benefits they may rarely use.
Medical Insurance: What Does It Usually Cover?
Medical insurance can cover different services depending on the policy. Common categories include:
Outpatient Care
Outpatient benefits can cover consultations, specialist visits, diagnostic tests and other eligible services that do not require hospital admission.
Inpatient Treatment
Inpatient coverage applies to eligible treatment requiring hospital admission. The policy should clearly state room categories, hospital networks, treatment limits and any applicable patient contribution.
Emergency Treatment
Emergency care is an important part of healthcare insurance. In Dubai’s basic insurance framework, emergency medical treatment is covered across the UAE within the applicable policy requirements.
Prescription Medicines
Some plans include prescription medicine benefits subject to annual limits, copayments, formularies or other restrictions. Always check whether commonly required medicines are included and what percentage of the cost you must pay.
Maternity Care
Maternity benefits vary significantly between policies. Buyers should check prenatal consultations, diagnostic tests, delivery, complications, newborn coverage and waiting periods where applicable.
Understanding the Provider Network
The hospital and clinic network is one of the most important factors when selecting insurance. A policy may look affordable, but its practical value can be limited if your preferred hospital or doctor is outside the network.
Before buying a plan, check whether the hospitals, clinics, pharmacies and diagnostic centres you normally use are included.
Dubai’s health insurance framework allows limited networks for basic coverage, but DHA states that the network should provide reasonable geographical access in relation to the insured person’s workplace and residence.
For a family, check the network separately for each location where you regularly live, work or study. A convenient network can reduce both travel time and unexpected out-of-network expenses.
Copayment, Coinsurance and Deductibles Explained
Insurance terminology can make comparing policies confusing. Three common terms are copayment, coinsurance and deductible.
Copayment
A copayment is a fixed amount that the insured person pays for an eligible service. For example, a policy may require a fixed payment when visiting a doctor, with the insurer covering the remaining eligible amount according to the policy.
Coinsurance
Coinsurance is generally a percentage of the eligible healthcare cost that the insured person must pay. The exact percentage and applicable services depend on the policy.
Deductible
A deductible is an amount the insured person must pay before the insurer begins paying for covered expenses under the applicable terms.
DHA’s insurance guidance explains the distinction between coinsurance and deductibles and notes that both can be used as mechanisms for managing healthcare costs.
How Much Does Health Insurance Cost in the UAE?
There is no universal price for health insurance. Premiums depend on factors such as age, coverage level, medical history, geographical coverage, provider network, benefits and policy limits.
Basic mandatory coverage can be considerably less expensive than comprehensive international insurance. However, comparing policies purely on annual premium can be misleading.
For example, a cheaper plan may require higher copayments or provide access to fewer hospitals. A more expensive policy may offer broader coverage that becomes valuable if you regularly require specialist treatment.
When comparing prices, calculate the potential total annual cost rather than looking only at the premium. This includes deductibles, copayments, coinsurance and other likely out-of-pocket expenses.
Pre-Existing Conditions and Health Insurance
Pre-existing medical conditions can affect eligibility, coverage, waiting periods or premiums depending on the policy and applicable regulations.
Applicants should provide accurate information when completing insurance applications. Failing to disclose relevant information can create complications during claims processing.
Never assume that a condition is automatically covered simply because the policy includes general medical treatment. Review the policy wording and exclusions carefully before purchasing.
Health Insurance for Employees
Employers play an important role in providing health coverage to employees. In Dubai, DHA states that employers are required to provide applicable health insurance coverage for employees, while sponsors have responsibilities concerning dependants in accordance with the relevant framework.
Employees should review the insurance benefits included with their employment package. Important details include the provider network, annual limit, outpatient benefits, hospital coverage, copayments and whether dependants can be added.
Employees should also ask whether the policy changes when they move to another employer. Employer-sponsored insurance is normally linked to the employment arrangement and should not be assumed to continue after employment ends.
Health Insurance for Families and Dependants
Family coverage requires careful comparison because dependants may have different healthcare needs.
Parents should review children’s outpatient and emergency coverage, specialist access, pharmacy benefits and hospital networks. Families planning to have children should pay particular attention to maternity and newborn provisions.
DHA guidance notes that employers are encouraged to cover spouses and dependants, but where an employer does not provide that coverage, the sponsor may need to arrange it.
This makes it important for residents to understand exactly who is included in an employer-sponsored policy rather than assuming that every family member receives the same benefits as the employee.
How to Compare the Best Healthcare Insurance Plans
Comparing policies systematically can help you avoid choosing based solely on price.
Step 1: Identify Your Healthcare Needs
Consider how often you visit doctors, whether you need specialist care, whether you take regular medication and whether you need maternity, dental or optical benefits.
Step 2: Check the Hospital Network
Make a list of your preferred hospitals and clinics and confirm whether they are included in the plan’s network.
Step 3: Compare Annual Limits
Review the maximum amount the insurer will pay under the policy. A higher annual limit can be important for people who want broader protection against major medical expenses.
Step 4: Review Out-of-Pocket Costs
Check deductibles, copayments and coinsurance. These amounts can significantly affect the real cost of using your insurance.
Step 5: Read Exclusions
Every insurance policy has exclusions or limitations. Understanding them before purchase is better than discovering them during a claim.
Step 6: Check Renewal Terms
Review how the policy renews, when premiums can change and what happens when your circumstances change.
Common Mistakes When Buying Medical Insurance
People often make avoidable mistakes when selecting health insurance.
- Choosing the cheapest policy without comparing benefits
- Failing to check the hospital network
- Ignoring copayments and deductibles
- Assuming every medical service is covered
- Overlooking waiting periods
- Not checking maternity or newborn conditions
- Failing to disclose relevant information accurately
- Buying a policy without reading exclusions
- Assuming an employer plan covers dependants automatically
These mistakes can lead to unexpected costs or limited access to preferred healthcare providers.
Healthcare Insurance and Digital Services
Insurance services are becoming increasingly digital. Insurers and healthcare providers may use online portals and applications for policy information, provider searches, approvals, claims and other administrative processes.
This digitalisation can make insurance easier to manage, but policyholders should still keep copies of important policy documents and understand how to contact the insurer or administrator when a problem occurs.
Digital healthcare is also changing the wider UAE healthcare environment. As discussed in our guide to healthcare technology, connected systems and digital services are becoming increasingly important across healthcare delivery.
Healthcare Insurance and the UAE Healthcare System
Insurance is closely connected with the wider healthcare ecosystem. Healthcare providers, insurers, third-party administrators, regulators and patients all interact within the system.
Dubai Health Authority reported that the number of beneficiaries covered under Dubai’s health insurance system exceeded 4.9 million in 2025, compared with approximately 4.6 million in 2024. DHA also reported approximately 49.6 million insurance claims in 2025.
These figures show the scale of healthcare insurance activity in Dubai and underline why understanding networks, claims processes and policy benefits is important for residents and employers.
What Should Employers Look for in Health Insurance?
Businesses selecting health insurance for employees should consider more than the annual premium. A useful corporate plan should balance cost with employee access to appropriate healthcare services.
Employers should compare provider networks, employee demographics, coverage limits, claims administration, customer service and renewal terms. They should also make sure the selected policy satisfies the applicable regulatory requirements.
For organisations with employees across multiple emirates, it is particularly important to understand the different insurance requirements that may apply in each location.
How to Choose the Best Healthcare Insurance for Your Situation
The best policy is the one that fits your actual healthcare needs and financial circumstances.
A young, healthy individual may prioritise affordable premiums and access to a reliable network. A family may place greater importance on paediatric, maternity and specialist benefits. Someone who travels frequently may prefer broader geographical coverage.
People with ongoing healthcare needs should pay particular attention to specialist access, medication coverage, annual limits, pre-existing condition provisions and out-of-pocket costs.
There is no reason to pay for extensive benefits that you are unlikely to use, but reducing coverage too aggressively can also create financial risk when unexpected treatment is required.
Summary
Choosing the best healthcare insurance in the UAE requires a careful comparison of coverage, provider networks, costs and policy conditions. The cheapest premium is not always the most economical option, and the most comprehensive policy is not necessarily the right choice for every resident.
Start by identifying your healthcare needs, then compare health insurance plans based on hospitals, clinics, annual limits, deductibles, copayments, exclusions and additional benefits. Employees should also understand what their employer-sponsored medical insurance actually covers and whether dependants are included.
Because health insurance requirements differ across the UAE, residents should confirm current rules with the relevant authority and carefully review the official policy documents before purchasing or renewing coverage.
A well-chosen medical insurance policy can provide financial protection while making access to healthcare more predictable. The goal should be to find a balance between affordability, useful coverage and reliable access to the healthcare services you are most likely to need.



5 thoughts on “Best Healthcare Insurance in UAE: Health Insurance Plans, Medical Cover and Tips”